FAIRWAY HOME MORTGAGE · GRAND JUNCTION

There’s more than one way to make the payment work.

Darrin Wade helps Western Colorado buyers look past the headline rate and toward practical financing paths that fit the life they are building.

WHERE TO START

A clear next move starts with your real financial picture.

Buying in a high-rate market can feel like a math problem with too many unknowns. Darrin makes it a conversation: your income, your savings, your timing, and the tools that may make homeownership more workable.

Text Darrin at 970-201-0660
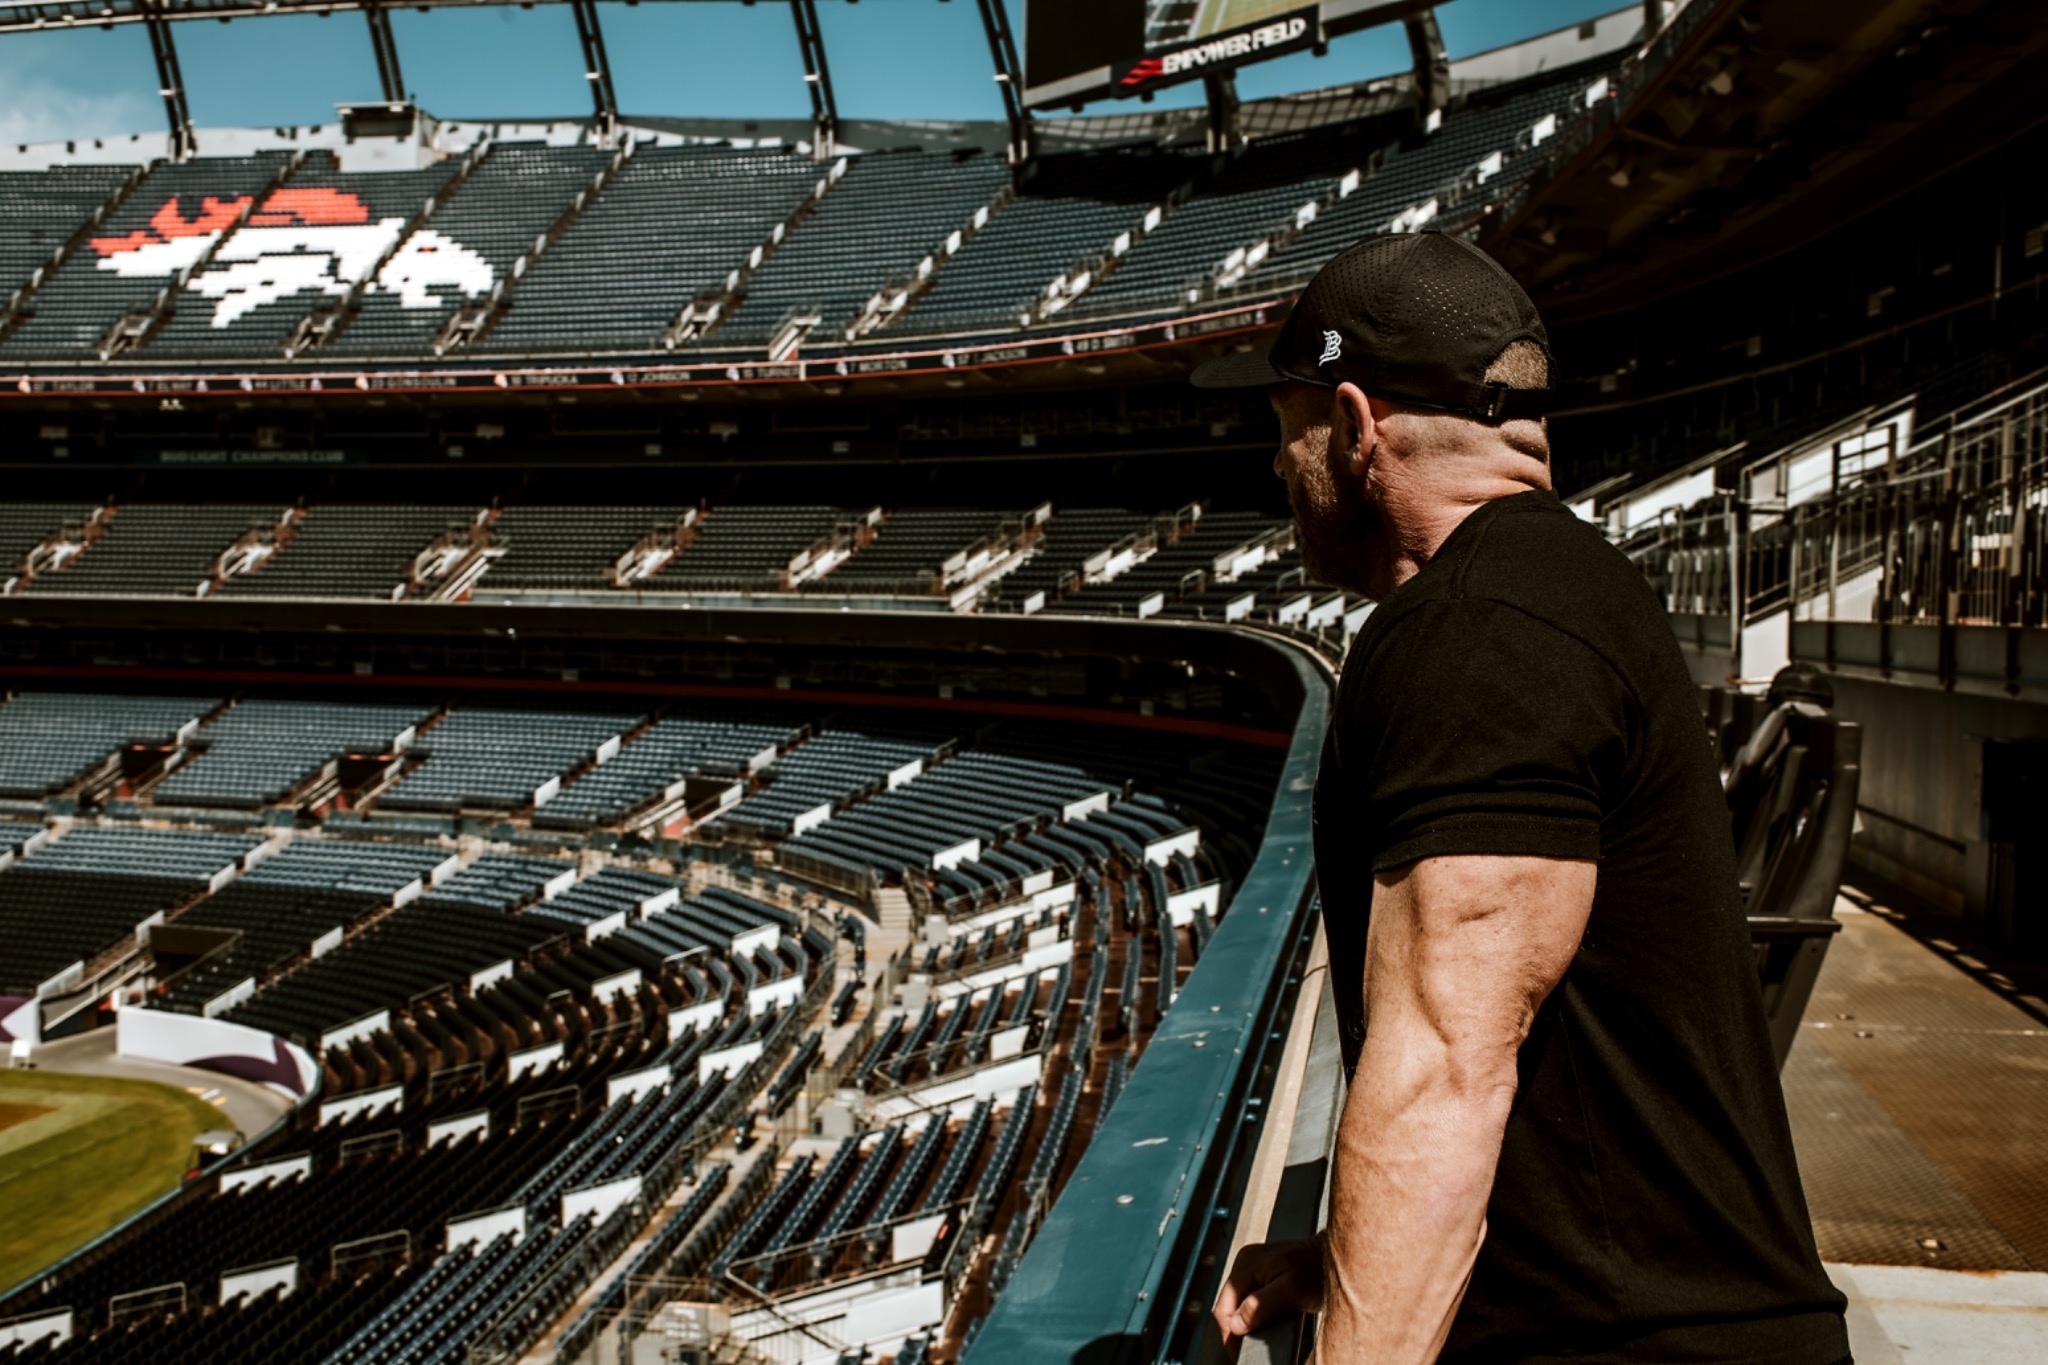
Darrin Wade overlooking a football stadium

SIX WAYS TO LOOK FORWARD

Options worth a closer look.

Every buyer is different. These are starting points—not one-size-fits-all answers.

FAIRWAY’S BUDGET BOOSTER

0.5% temporary buydown

A 0.5/0 temporary buydown can give eligible buyers a lighter principal-and-interest payment in the first year. Your loan is still qualified using the full note-rate payment, so the long-term payment stays in view from the beginning.

For months 1–12, the payment is calculated as if the rate were 0.50 percentage points lower. Fairway funds the difference. Starting in month 13, the payment returns to the full note-rate amount—without changing the note rate or assuming a refinance.

Principal and interest only. Taxes, insurance, mortgage insurance, HOA dues, closing costs, eligibility, and availability must be reviewed for your scenario.

Ask Darrin about the full 0.5% buydown guide
FAIRWAY BUY & SAVE™

No mortgage payments for up to three months

For eligible buyers, Fairway Buy & Save™ can cover up to the first three complete mortgage payments on a new home. It is designed to give qualifying buyers a little more room during the first months of homeownership.

The payment due date on the note does not change. Program requirements, qualifying criteria, and restrictions apply.

Text Darrin at 970-201-0660

FAIRWAY ARM OPTION

A 7/1 ARM can keep your rate fixed for the first seven years

A 7/1 adjustable-rate mortgage keeps the interest rate fixed for the first seven years. After that, the rate may adjust once each year under the loan terms. It may be worth a conversation if you expect your homeownership or mortgage plan could change before the adjustment period.

After the fixed period, the rate and payment may increase or decrease. Initial rate, index, margin, adjustment caps, program availability, qualification, and costs must be reviewed for your scenario.

Text Darrin at 970-201-0660

INCOME THAT DOESN’T FIT A BOX

Bank statement loan programs

Self-employed, commission-based, or building a business? Traditional tax returns may not always show the whole story. Bank statement programs can use qualifying deposit history and other documentation to help assess repayment ability.

Program requirements, documentation, credit, assets, down payment, and pricing vary.

Text Darrin at 970-201-0660

A $1,000 STARTING POINT

Eligible CHFA buyers may have a required borrower contribution of as little as $1,000

CHFA’s statewide first-mortgage programs require a minimum borrower financial contribution of $1,000 toward a home purchase. For eligible buyers, CHFA grants or second mortgage loans may help with down payment and closing costs.

CHFA program, Participating Lender, credit, income, homebuyer education, property, and underwriting requirements apply. Final contribution and assistance are determined for your approved scenario.

Text Darrin at 970-201-0660
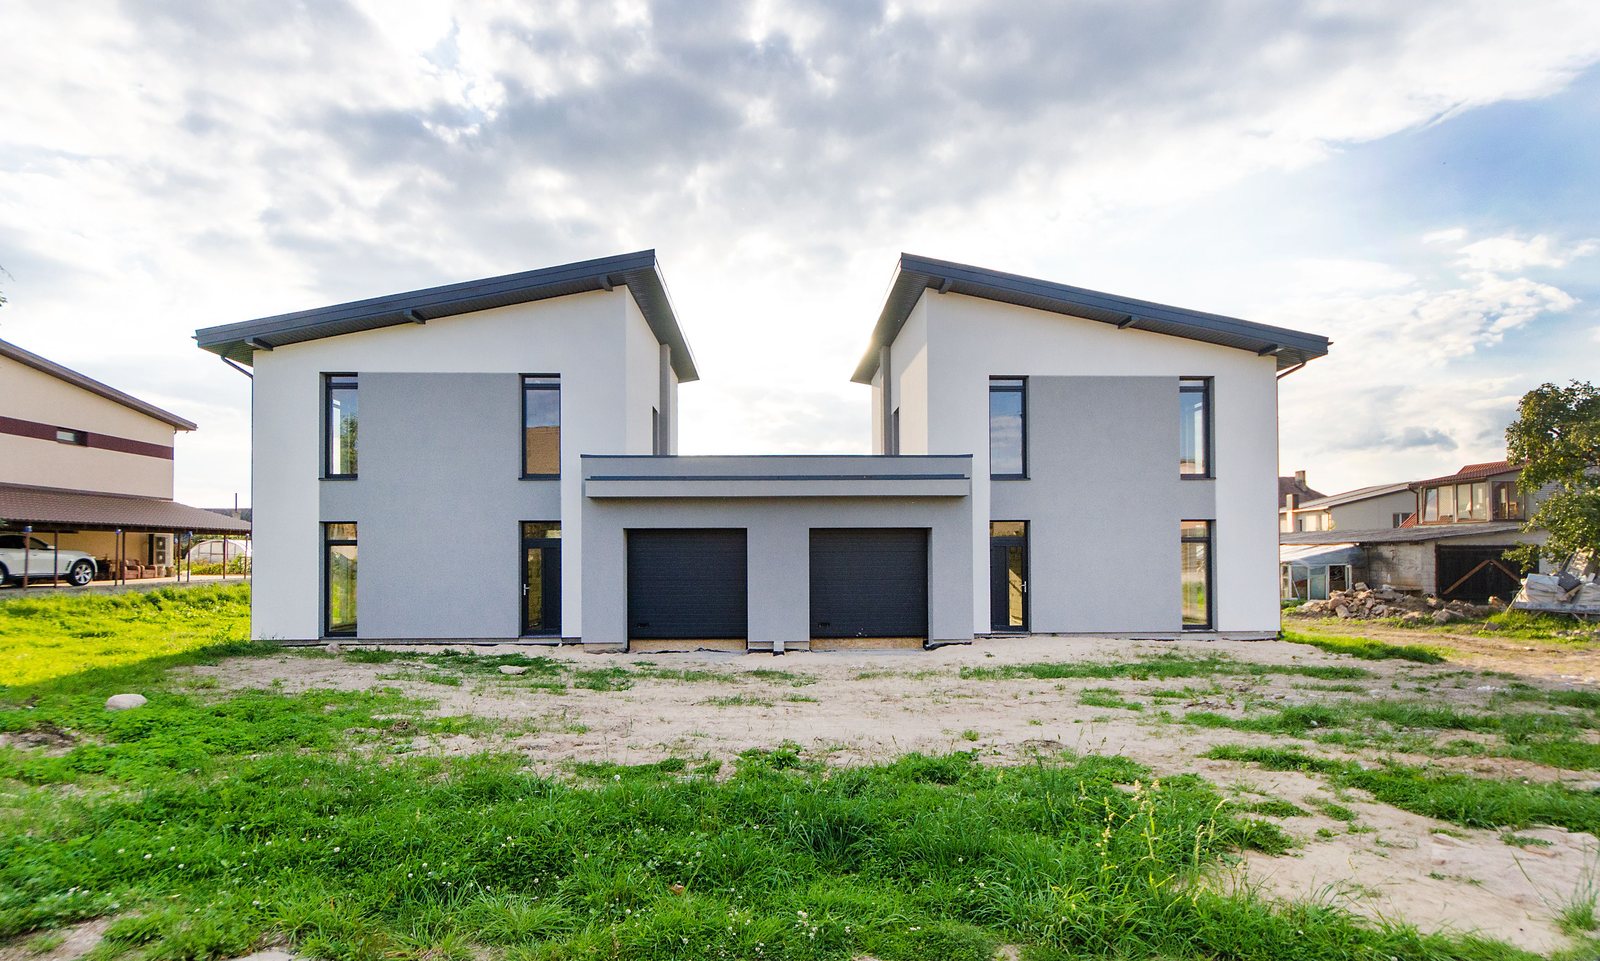
Modern new home exterior

FAIRWAY NON-QM SPOTLIGHT

For buyers with strong assets but limited traditional income

If your financial strength is primarily in eligible, seasoned assets rather than traditional monthly income, an asset-based non-QM path may be worth exploring. Darrin can help determine whether an available Fairway option is appropriate for your situation.

Non-QM loans are fully underwritten and are not a fit for every buyer. Terms and availability can change.

Text Darrin at 970-201-0660

THE DARRIN DIFFERENCE

Less guessing.
More grounded decisions.

Darrin helps you compare paths in plain language—so you understand what may work, what it takes, and what to ask next.

Start with the full payment, the cash to close, and the timing that fit your actual plan—not just today’s headline rate.

YOUR NEXT CONVERSATION

Let’s make the market feel more manageable.

Text Darrin with your homebuying questions. Together, you can look at the options that may fit your timeline, documentation, and down payment plan.

START WITH DARRIN

Bring the questions you have now.

Text Darrin 970-201-0660

Darrin Wade
Area Manager · NMLS #277275

601 Main Street, Suite A
Grand Junction, CO 81501

Office 970-778-3440 · Toll-free 866-396-6314
dwade@fairwaymc.com